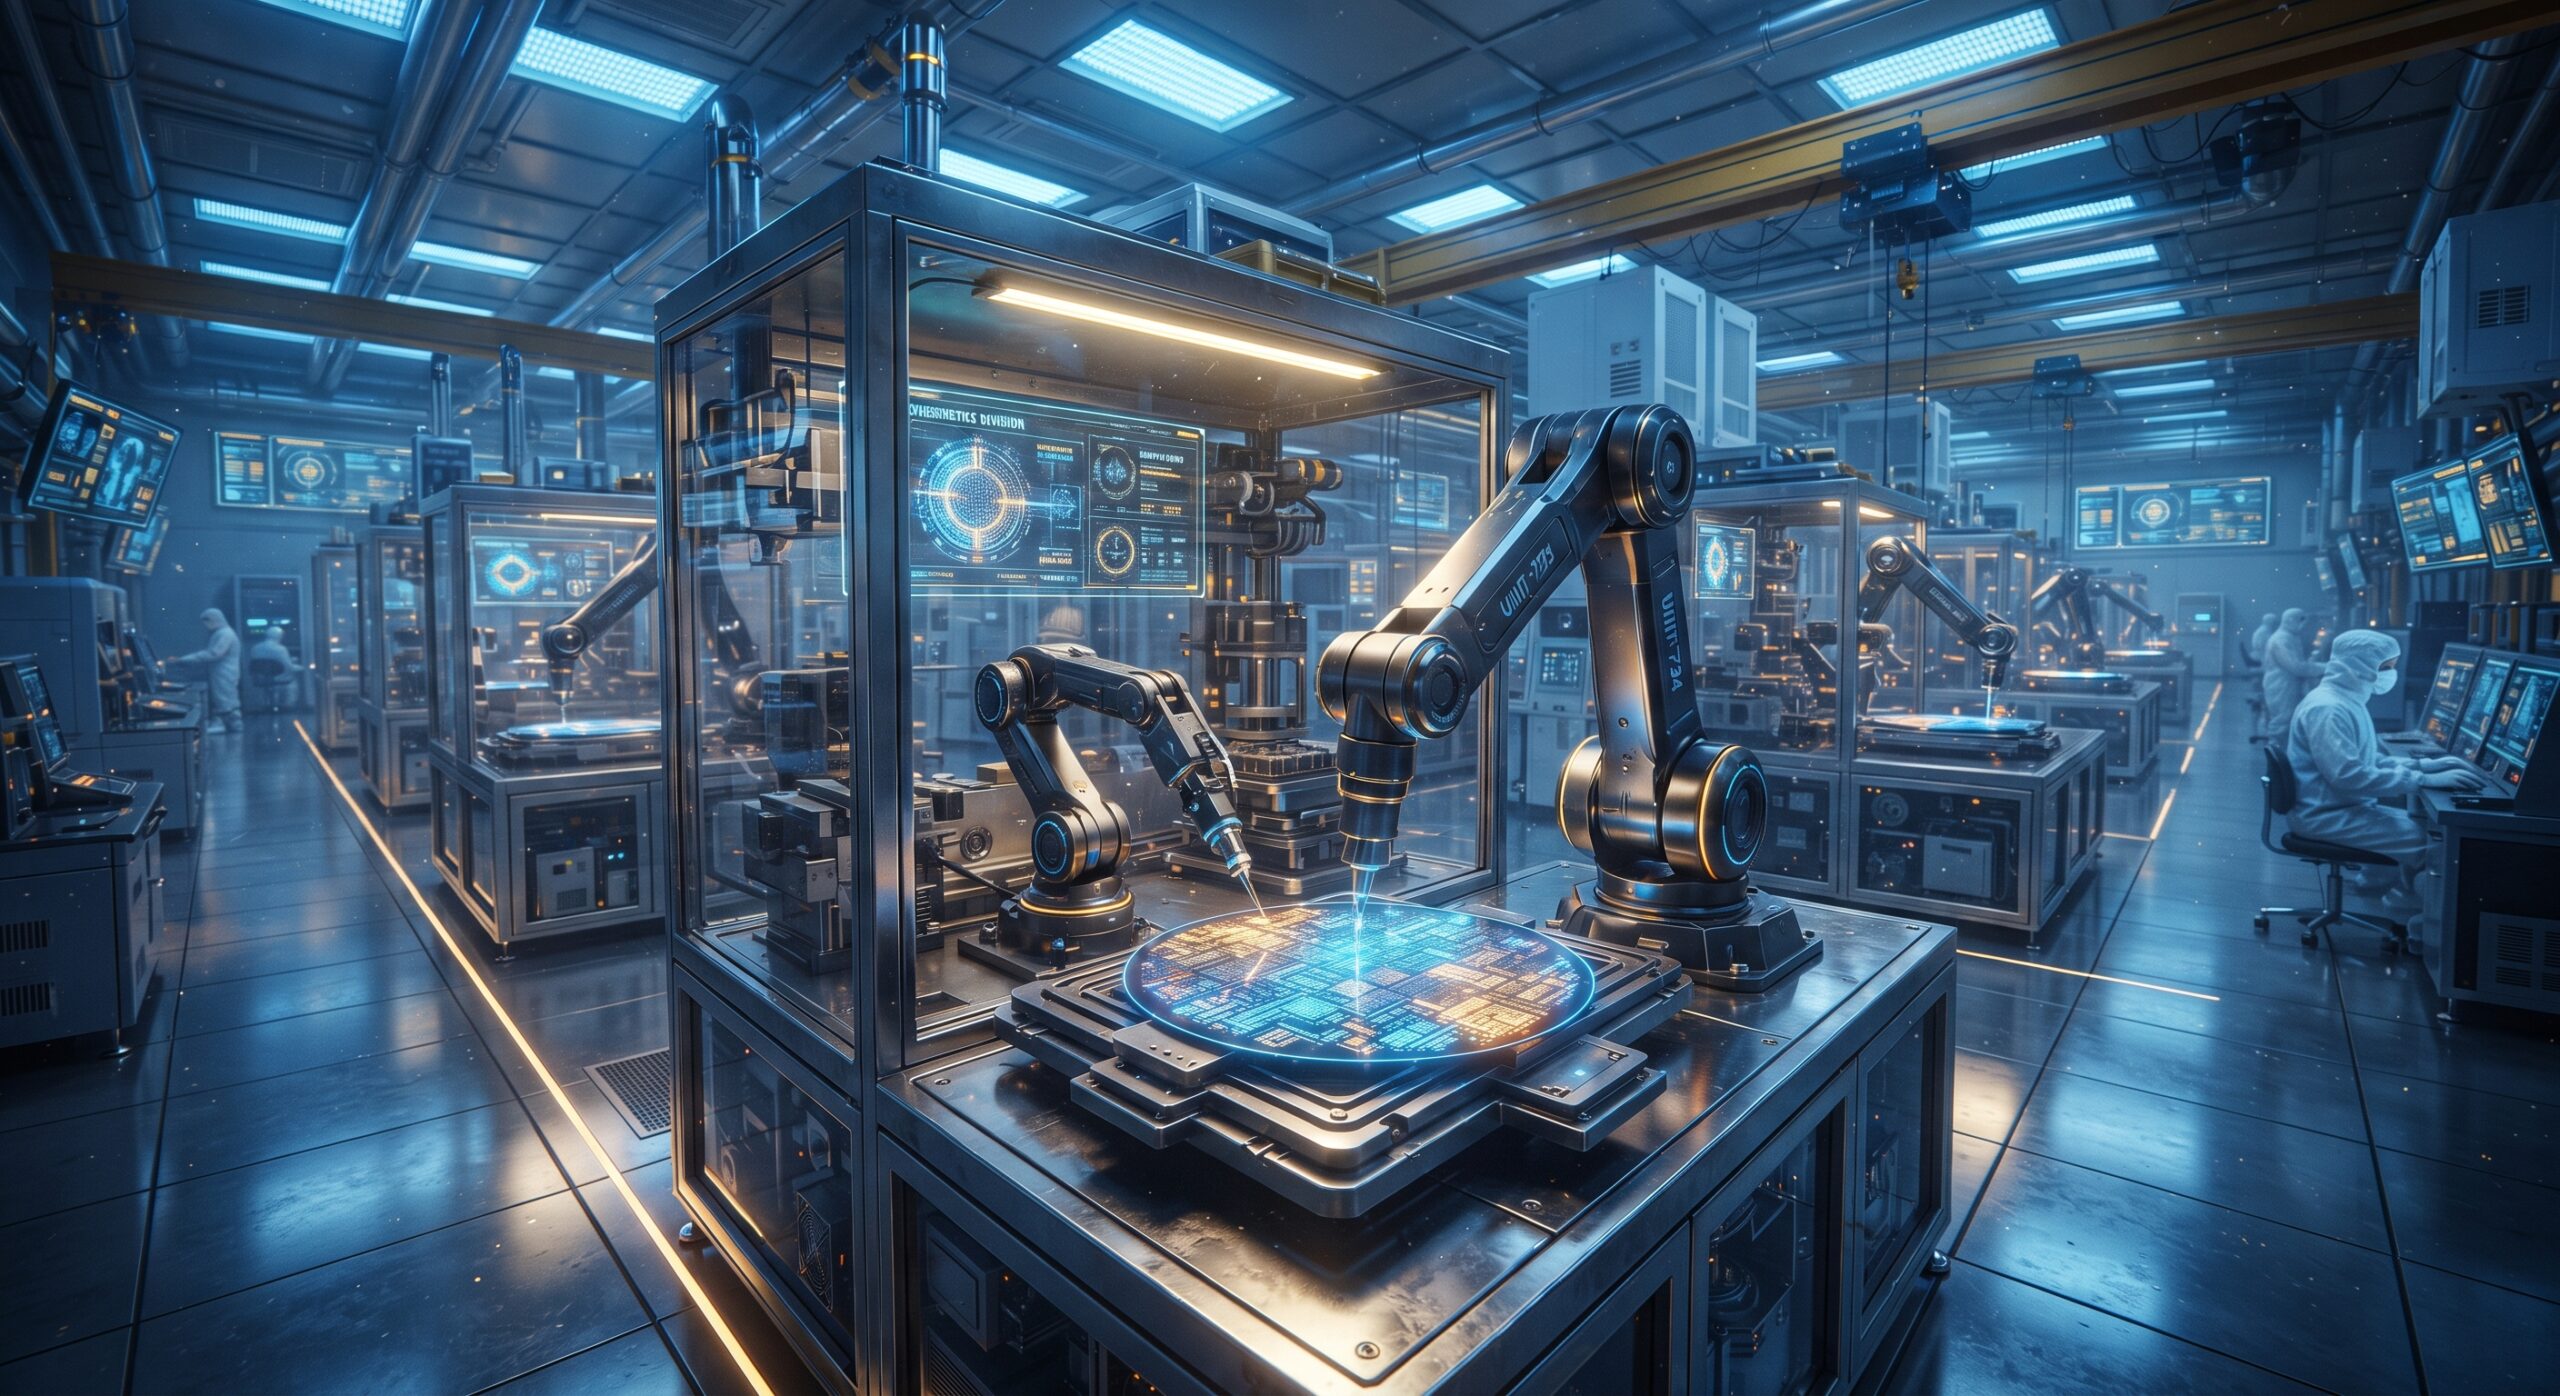
The global semiconductor industry—widely considered the most complex manufacturing process on Earth—is undergoing a massive transformation. Driven by an insatiable, multi-billion-dollar boom in artificial intelligence, the chip sector is projected to hit $1 trillion in revenue. However, this unprecedented demand is pushing supply chains, physical manufacturing limitations, and geopolitical fault lines to their absolute limits.
The Heartbeat of the Global Economy
Semiconductors are the foundational building blocks of modern civilization, found in everything from smartphones and robot vacuums to advanced supercomputers and defense systems. Approximately one trillion semiconductor devices are shipped every year—roughly 100 devices for every person on Earth.
While traditional chip demand used to be driven by consumer electronics like phones and PCs, the AI explosion has fundamentally shifted the market. Data center infrastructure spending is soaring past the $1 trillion mark, and AI chips now account for a massive share of production, turning the semiconductor market into a sustained growth engine rather than a cyclical rollercoaster.
The Choke Points of Advanced Manufacturing
Producing cutting-edge semiconductors requires a hyper-specialized, highly concentrated global supply chain where a single disruption can ripple across the entire world.
- The Lithography Monopoly (ASML): Headquartered in Europe, ASML builds the world’s most complex machines—such as Extreme Ultraviolet (EUV) lithography systems—which use light to print patterns onto silicon wafers at sub-microscopic scales. Costing up to $400 million each and weighing as much as a blue whale, these machines are essential for manufacturing the world’s most advanced chips. Every leading-edge chipmaker relies on ASML’s technology.
- The Fabrication Bottleneck (TSMC): Taiwan Semiconductor Manufacturing Company (TSMC) manufactures over 90% of the world’s most advanced chips out of its massive “gigafabs” in Taiwan. Because building a new fabrication plant requires immense experience, capital (upwards of $30 billion), and precision timing, TSMC remains the central bottleneck of global chip production.
- Geopolitical Vulnerabilities: This heavy geographical concentration in Taiwan places the global economy in a precarious position. Geopolitical tensions and regional friction threaten a supply chain that experts warn could cost trillions of dollars in global economic fallout if disrupted.
The Race for Self-Reliance and Reshoring
Recognizing semiconductors as a critical matter of national security and economic survival, global superpowers are racing to build domestic manufacturing capabilities.
- The United States: Through legislation like the 2022 Chips Act, the U.S. is aggressively pushing to reshore chip manufacturing. Major investments—such as TSMC’s massive $165 billion commitment in the Arizona “Silicon Desert”—are transforming regional landscapes to bring advanced production onto American soil. Meanwhile, legacy American giants like Texas Instruments are investing tens of billions into upgrading analog and essential chip manufacturing.
- China’s Domestic Push: Despite strict U.S. sanctions and export controls blocking access to advanced Western equipment like ASML’s lithography machines, China has aggressively pursued technological self-reliance. Backed by massive government funds and domestic tech giants, Chinese manufacturers have made surprising strides in developing homegrown advanced chip capabilities.
Innovating Beyond the Limits
As physical boundaries, energy constraints, and extreme costs test the limits of physics and chemistry, the semiconductor industry continues to adapt. From scaling up wafer sizes to 300mm to maximize efficiency, to powering the data centers driving the next generation of AI, the stakes have never been higher.
The chip industry has evolved from an obscure technological backwater into the defining infrastructure of the modern global economy.
Leave a Reply