
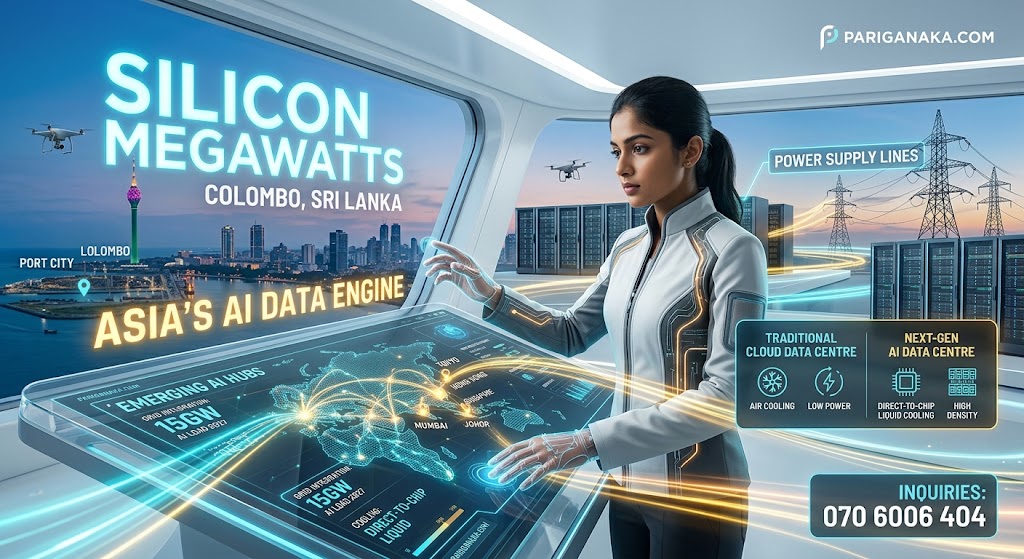
As artificial intelligence shifts from experimental generative models to high-throughput industrial infrastructure, the digital economy’s gravity is pulling sharply toward Asia. While Silicon Valley leads the charge in algorithmic design, the Asian continent is rapidly cementing its dominance as the physical engine powering the compute-intensive future.
Driven by surging domestic digital adoption, strategic land availability, and access to expanding power grids, Asia’s data centre boom is transforming real estate, energy markets, and sovereign digital strategies.
The Catalysts Behind Asia’s Data Centre Boom
1. Sourcing Power in an Energy-Constrained World
The primary bottleneck for AI globally is no longer chip supply—it is high-voltage electricity. Western hubs face saturated power grids and protracted utility queues. In response, hyperscalers (including Microsoft, Google, and Amazon) are directing billions into Asia, seeking regions where power generation can scale in tandem with massive data workloads.
2. The Relocation from Mature Hubs to Emerging Corridors
Historically, Singapore, Hong Kong, and Tokyo served as Asia’s undisputed data capitals. However, land constraints, high real estate costs, and strict environmental limits (such as Singapore’s prior moratorium on new data centres to curb carbon emissions) have pushed development outward:
- Malaysia (Johor Bahru): Rapidly emerging as Southeast Asia’s premier data corridor due to its proximity to Singapore, affordable land, and dedicated cross-border power connections.
- India: Capitalizing on its massive internal consumer base, strong renewable energy commitments, and pro-infrastructure policies to build gigawatt-scale data campuses in hubs like Navi Mumbai and Chennai.
- Indonesia & Vietnam: Attracting regional investment by positioning themselves as low-latency hubs for rapidly expanding mobile-first populations.
3. Data Sovereignty and Cross-Border Compliance
Nations across Asia are tightening data governance regulations, mandating that sensitive citizen data, financial records, and critical AI training sets remain within sovereign borders. Building local data infrastructure is no longer just a cost decision; it is a regulatory prerequisite for multinationals operating across Asian markets.
Infrastructure Divide: Old Data vs. AI Workloads
| Metric | Traditional Cloud Data Centre | Next-Gen AI Data Centre |
| Power Density | 5 – 10 kW per rack | 40 – 100+ kW per rack |
| Cooling Architecture | Standard air conditioning | Direct-to-chip liquid cooling & immersion systems |
| Compute Profile | General-purpose CPUs for web apps & storage | High-density GPU/NPU clusters for matrix mathematics |
| Grid Integration | Standard grid connections | Dedicated substation ties, battery storage & micro-grids |
The Ecological and Regulatory Crossroads
The influx of gigawatt-scale facilities brings significant friction. High-density compute campuses consume millions of gallons of water for cooling and draw massive loads from local grids, often competing directly with municipal and domestic needs.
Governments across the region are responding by demanding higher sustainability standards:
- Transitioning from traditional evaporative cooling to closed-loop liquid and immersion cooling.
- Mandating corporate power purchase agreements (PPAs) tied directly to off-grid solar, wind, and hydroelectric expansion.
- Enforcing strict Power Usage Effectiveness (PUE) ratios before approving construction permits.
Asia’s surge in data centre construction demonstrates that the AI revolution is fundamentally an infrastructure race. Algorithms define what artificial intelligence can theoretically achieve, but the physical concrete, high-voltage transformers, and liquid-cooled racks rising across Asia will dictate how fast that future actually arrives.
Leave a Reply